High Street Bank vs Specialist Lender: The Honest Comparison for Property Investors in 2026
Introduction: The Cheapest Lender Is Not Always the Right Lender
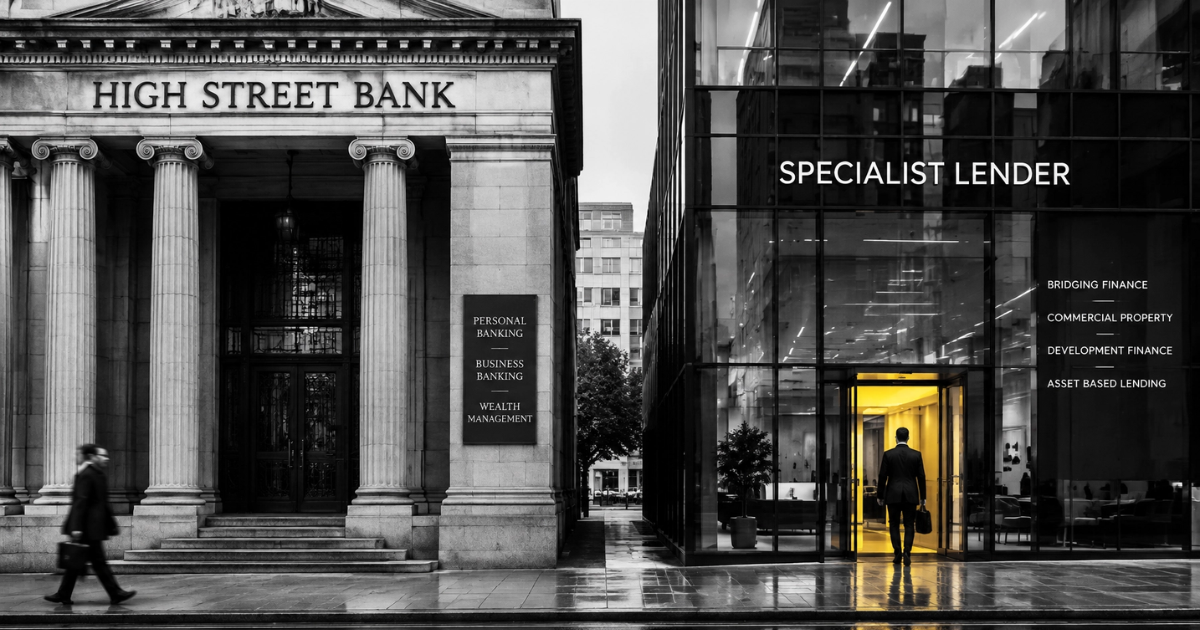
Should you fund your property investment through a high street bank or a specialist lender?
For a straightforward buy-to-let purchase, a high street bank will often offer the more attractive interest rate. Its products are designed for standard, mortgageable properties and borrowers who meet established lending criteria.
But what happens when the property is being purchased at auction, needs substantial refurbishment or must complete within 28 days?
That is where the comparison changes.
A specialist lender may offer the speed, flexibility and case-by-case assessment that a conventional bank cannot provide within the required timeframe. It may consider properties that are currently unmortgageable, complex titles, refurbishment projects and transactions where the repayment strategy depends on improving or selling the asset.
The honest answer is that neither lending model is universally better. They are designed to solve different problems.
For many property investors, the most effective approach is to use specialist finance to acquire and improve a property, then refinance onto a longer-term mortgage once the asset meets mainstream lending requirements.
This guide compares the two lending models, examines where each performs best and explains why choosing the wrong funding route can cost considerably more than the difference between two headline interest rates.
This guide reflects the UK property finance market position at November 2026. Comparisons are indicative and describe broad lending segments, not guaranteed terms from individual lenders. Actual rates, fees, criteria and completion times depend on the borrower, property, transaction and lender.
"The bank buys a payment stream. The specialist buys an exit. An auction contract is a plan with dates, and dates are the specialist's language."
— Deji Nehan, Auction Demystified: Unlocking Auction Success
Key Takeaways
| Key point | What it means for property investors |
|---|---|
| The lending models differ | Banks generally focus on standardised mortgage criteria; specialists assess individual transactions and exit strategies |
| Banks often win on headline rates | Standard, mortgageable buy-to-let and residential cases may be cheaper through mainstream lenders |
| Specialists offer greater flexibility | Bridging, refurbishment, development and complex property cases may need specialist underwriting |
| Auction deadlines change the equation | A competitive mortgage rate is irrelevant if the lender cannot complete within the contractual deadline |
| The hybrid approach can work well | Use specialist finance for acquisition and refurbishment, then refinance onto suitable longer-term finance |
| The right lender can reduce total cost | Matching the property and transaction to the appropriate lender may avoid delays, failed applications and unnecessary interest |
1. Understanding the Two Lending Models
The difference between a high street bank and a specialist lender goes beyond the interest rate.
They generally approach property finance from different underwriting perspectives, offer different products and are equipped to deal with different types of transactions.
What does a high street bank offer property investors?
A high street bank typically operates a standardised lending model.
It offers established products, such as:
- Residential mortgages.
- Buy-to-let mortgages.
- Remortgages.
- Portfolio lending.
- Standard property refinancing.
Applications are assessed against defined lending criteria. These may include borrower income, credit history, affordability, rental coverage, property valuation and the suitability of the security.
For a conventional residential property or a straightforward buy-to-let investment, this approach can be highly effective.
Banks benefit from scale, established processes and access to funding that can support competitive long-term mortgage pricing.
However, standardisation has limitations. A property that falls outside a bank's normal security requirements may be declined, regardless of how attractive the investment appears to the buyer.
What does a specialist lender offer?
A specialist lender focuses on transactions that may not fit conventional mortgage criteria.
Its products can include:
- Bridging loans.
- Auction finance.
- Refurbishment finance.
- Heavy refurbishment facilities.
- Development finance.
- Commercial bridging.
- Complex buy-to-let mortgages.
- Finance for certain unusual or non-standard properties.
Specialist underwriting can consider the property's condition, title, proposed works, borrower experience, transaction timetable and intended repayment strategy.
For example, a property that is currently uninhabitable may not qualify for a conventional mortgage. A specialist lender may nevertheless consider funding it through an appropriate refurbishment or development facility, subject to its criteria and the overall viability of the transaction.
This flexibility comes at a price. Specialist finance generally carries higher interest rates and fees than a conventional long-term mortgage.
The important distinction is that the specialist lender may be providing finance for a transaction that the bank cannot support in its current form.
2. High Street Bank vs Specialist Lender: The Side-by-Side Comparison
The following table summarises the broad differences between the two lending models.
| Comparison | High street bank | Specialist lender |
|---|---|---|
| Underwriting approach | Standardised criteria and affordability assessment | Individual case assessment, asset and exit analysis |
| Typical products | Residential and buy-to-let mortgages, standard remortgages | Bridging, auction, refurbishment, development and complex property finance |
| Typical speed | Often weeks to months | Can be days to weeks, depending on complexity |
| Property condition | Generally requires mortgageable security | May consider uninhabitable or non-standard properties |
| Title flexibility | Usually standard title requirements | Some title issues may be assessed individually |
| Headline interest rate | Generally lower for standard cases | Generally higher, reflecting short-term funding and risk |
| Arrangement fees | Often lower or structured around mortgage products | Can include percentage-based arrangement fees and other charges |
| Exit strategy | Long-term repayment through mortgage payments or sale | Often central to underwriting, particularly for bridging |
| Refurbishment funding | Not normally designed for substantial works during acquisition | Specific refurbishment and development products may be available |
| Auction suitability | Possible for suitable, pre-assessed properties with sufficient time | Often better suited to tight auction deadlines and complex lots |
| Case flexibility | Defined lending criteria | Greater scope for individual assessment within lender appetite |
| Typical relationship | Product and account focused | Often transaction and case focused |
These are broad market tendencies, not universal rules. Some mainstream banks offer specialist or flexible products, and some specialist lenders have strict criteria of their own.
The correct comparison is always between the actual products available for the specific transaction.
3. Where Each Lender Wins: Matching the Finance to the Property
The most useful way to compare lenders is to look at the property investment scenario rather than the institution's name.
Scenario A: Buying a habitable buy-to-let property
<badge color="success">High street bank often preferred</badge>
Suppose an investor is purchasing a standard two-bedroom rental property through an estate agent.
The property is in good condition, has a straightforward title and can be valued using comparable evidence. The investor has sufficient time to complete a conventional mortgage application.
A high street bank may be the better option.
Why?
- The property meets standard mortgage security requirements.
- The transaction does not depend on an unusually fast completion.
- The borrower can satisfy the lender's affordability criteria.
- The lower long-term interest rate can make a meaningful difference over several years.
In this situation, using a short-term bridging loan may introduce unnecessary interest and fees.
Scenario B: Buying at auction with a short completion deadline
<badge color="success">Specialist lender often preferred</badge>
An investor wins a property at auction and must complete within the contractual period, which may be 20–28 days or another timeframe specified in the conditions of sale.
The property may be mortgageable, but the investor still needs a lender capable of assessing the transaction and completing within the available time.
A conventional mortgage application may not fit that timetable.
A specialist auction finance or bridging facility may provide a more appropriate route, provided the borrower, property, valuation, legal work and exit meet the lender's requirements.
The key advantage is not simply a higher willingness to lend. It is the ability to structure funding around the transaction's deadline.
Some bank mortgages can support auction purchases where the property is suitable and the finance is arranged sufficiently early. The issue is not that banks can never fund auctions; it is that their normal processing times and security requirements may not suit many auction transactions.
Scenario C: Buying an uninhabitable property
<badge color="success">Specialist lender often preferred</badge>
Consider an auction property that needs extensive refurbishment before it can be occupied or rented.
A conventional mortgage lender may decline the property because it does not meet its minimum condition or security requirements.
A specialist lender may consider a refurbishment bridging facility, potentially with funding for works depending on the product and lender criteria.
This can allow the investor to:
- Purchase the property.
- Complete the required refurbishment.
- Improve its condition and marketability.
- Arrange a longer-term mortgage or sell the property.
- Repay the bridging facility.
The lender will still assess the project, including the property's value, works, borrower contribution and proposed exit.
Scenario D: Refurbishing before letting
<badge color="success">Hybrid approach often preferred</badge>
This is one of the clearest examples of why investors may need both lending models.
A specialist lender funds the purchase and refurbishment. Once the property has been improved and meets the relevant mortgage criteria, the investor applies for a buy-to-let mortgage.
The specialist provides short-term funding for the difficult stage. The longer-term lender provides the more economical finance for the holding period.
Scenario E: Refinancing a clean property portfolio
<badge color="success">High street bank often preferred</badge>
An investor already owns a portfolio of standard, mortgageable rental properties.
The properties are in good condition, the titles are straightforward and the rental income supports the proposed borrowing.
A mainstream bank may offer competitive portfolio refinancing, subject to its criteria.
Paying specialist bridging rates for a transaction that can be completed through ordinary mortgage finance may be unnecessary.
Scenario F: Complex titles, HMOs and semi-commercial properties
<badge color="success">Specialist lender often preferred</badge>
Properties with unusual titles, multiple occupation arrangements or mixed residential and commercial use may fall outside the standard criteria of some high street lenders.
Specialist lenders may have products designed for these asset types.
However, specialist appetite varies significantly. A lender willing to consider one type of HMO or semi-commercial property may not accept another.
The property must be matched to the lender's actual criteria rather than assuming that every specialist lender will accept complex security.
Scenario G: Property development
<badge color="success">Specialist development finance often preferred</badge>
Ground-up development, conversion and major refurbishment projects require a different funding structure from an ordinary buy-to-let mortgage.
Development finance may take account of:
- Land or property value.
- Planning position.
- Build costs.
- Borrower experience.
- Gross development value.
- Drawdown stages.
- Development timetable.
- Repayment or sales strategy.
A conventional residential mortgage is generally not designed to fund this type of project.
4. The Rate Question: Cheaper Is Not Always Cheaper
The headline interest rate is often the first thing investors compare.
It is also one of the easiest ways to reach the wrong conclusion.
A high street mortgage at a lower annual rate may look far more attractive than a bridging loan charging a monthly rate. But the products may not be interchangeable.
Consider an investor who has purchased an auction property requiring substantial refurbishment.
A conventional bank mortgage may be cheaper, but if the property is currently unmortgageable or the lender cannot complete within the contractual deadline, that mortgage cannot solve the immediate funding problem.
Comparing the two interest rates is therefore misleading.
The correct question is:
Which finance product can complete the transaction and support the investment strategy at the lowest realistic total cost?
Understand the full cost of specialist finance
Specialist finance can involve several charges:
- Monthly interest.
- Arrangement or facility fee.
- Valuation fee.
- Lender legal costs.
- Broker fee, where applicable.
- Administration charges.
- Exit or redemption fee, where applicable.
- Extension costs if the facility runs beyond its original term.
The way interest is charged also matters. It may be serviced monthly, retained from the advance or rolled up, depending on the facility.
A borrower should compare the actual redemption figure and cash required, not just the advertised monthly rate.
Understand the full cost of a bank mortgage
A conventional mortgage also needs to be assessed beyond its headline rate.
Relevant costs can include:
- Product or arrangement fee.
- Valuation fee.
- Legal costs.
- Broker fee, where applicable.
- Early repayment charges.
- Product transfer or remortgage costs.
- Ongoing interest and mortgage payments.
The investor should also consider whether the bank's completion timetable is realistic for the transaction.
A low-rate mortgage that cannot complete before the contractual deadline is not a cheaper solution.
5. The Hybrid Reality: How Property Investors Use Both
For many auction-sourced buy-to-let investments, the most practical structure is not high street bank versus specialist lender.
It is specialist lender first, longer-term mortgage lender second.
This is commonly known as a bridge-to-term-mortgage strategy.
The typical two-stage funding structure
| Stage | Funding | Purpose |
|---|---|---|
| Acquisition at auction | Specialist bridging finance | Complete within the auction deadline, subject to lender approval |
| Refurbishment | Bridging facility with works funding, where available | Improve the property's condition and value |
| Mortgage preparation | Valuation and mortgage application | Establish whether the property meets long-term lender criteria |
| Long-term holding | Buy-to-let or other suitable term mortgage | Replace the short-term bridge |
| Final repayment | Mortgage proceeds | Redeem the bridging facility |
The specialist lender funds the short, demanding stage of the investment. The long-term mortgage lender provides the finance for the period when the property is suitable for mainstream borrowing.
The investor pays for specialist finance because it enables the acquisition and improvement to happen. Once that stage is complete, the debt can potentially move to a lower-cost long-term product.
This is not an automatic process. The refinance must be assessed and approved, and the investor should investigate the proposed mortgage route before purchasing.
Worked example: The cost of the specialist phase
Consider an investor who needs an £84,000 bridging facility to purchase and improve an auction property.
Assume:
- Gross bridging advance: £84,000.
- Monthly interest rate: 0.85%.
- Loan term: 9 months.
- Interest serviced monthly.
- No compounding or interest added to the principal.
The illustrative interest calculation is:
£84,000 × 0.85% × 9 = £6,426.
<box border radius="lg" padding={3} gap={2}>
<text color="secondary" weight="medium" size="sm">Illustrative bridging interest over nine months</text>
<title size="2xl" color="default" tabularNums>£6,426</title>
<text color="secondary" size="xs">£84,000 facility at 0.85% per month, with monthly serviced interest</text>
<divider color="subtle"/>
| Calculation | Amount |
|---|---:|
| Monthly interest | £714 |
| Nine-month interest | £6,426 |
| Principal to repay | £84,000 |
| Total principal plus interest | £90,426 |
<text color="secondary" size="xs">Excludes arrangement fees, exit fees, valuation, legal and other charges. Actual lender terms may differ.</text>
</box>
A conventional buy-to-let mortgage may cost considerably less in interest over the long term, but it may not be available for the initial auction purchase.
The purpose of the bridging facility is to get the investor through the acquisition and refurbishment stage.
Once the property is suitable for a long-term mortgage, refinancing may reduce the ongoing cost of borrowing.
The bridge is a temporary funding tool, not necessarily the destination.
Why investors should plan the refinance before taking the bridge
The hybrid structure only works if the second stage is realistic.
Before committing to the bridging facility, the investor should investigate:
- Whether the improved property will be mortgageable.
- The likely end valuation.
- The expected rental income.
- The lender's loan-to-value limits.
- Rental stress testing and affordability.
- The investor's credit and financial position.
- The time required for valuation, underwriting and legal completion.
A lower-than-expected valuation can reduce the mortgage advance and leave the investor needing additional funds to redeem the bridge.
The exit should therefore be planned from the beginning.
6. The Cost of Choosing the Wrong Lender
Selecting an unsuitable lender can create costs that are much larger than the difference between two interest rates.
| Wrong choice | What could happen | Potential cost |
|---|---|---|
| Applying to a bank for an unsuitable auction lot | Application cannot meet the property or completion requirements | Lost transaction, wasted application costs and possible contractual exposure |
| Applying to a bank for uninhabitable security | Property fails the lender's mortgageability criteria | Delays and professional costs before finding another funding route |
| Using bridging finance for a standard long-term refinance | Paying specialist rates for a straightforward mortgage transaction | Unnecessary interest and fees |
| Using one lender for every stage | Funding may not suit the acquisition, refurbishment and holding phases equally well | Higher overall borrowing cost or an unsuitable finance structure |
| Failing to plan the refinance | New mortgage does not complete before bridge maturity | Extension costs, additional interest and potential repayment difficulties |
The key lesson is that the funding structure should follow the investment strategy.
A specialist lender should not automatically be used just because a property is being purchased at auction. Equally, a high street bank should not be selected purely because its headline rate is lower.
The property, timescale and repayment strategy determine the appropriate route.
7. How Each Lending Model Looks at the Same Property
Imagine two investors assessing the same tired two-bedroom terrace.
The property needs refurbishment before it can be let. It is being sold at auction, with a short completion deadline.
The high street bank and specialist lender may approach the same transaction differently.
| Question | High street bank's likely focus | Specialist lender's likely focus |
|---|---|---|
| Can the borrower afford the repayments? | Income, affordability and stress testing | Borrower strength remains relevant, alongside the proposed exit |
| Is the property suitable security? | Habitable condition and standard mortgageability | Condition, value, works and whether the asset fits its criteria |
| Can the transaction complete in time? | Standard processing and underwriting requirements | Whether the case can be assessed and funded within the required timetable |
| What is the repayment plan? | Mortgage repayments and long-term affordability | How the bridge will be redeemed, commonly through refinance or sale |
| What happens if the project changes? | Subject to product and lending rules | May be considered individually, but any variation requires lender agreement |
| What is the funding designed to achieve? | Long-term property borrowing | Short-term acquisition, improvement or specialist property funding |
The distinction is not that banks ignore the property or that specialist lenders ignore the borrower. Both assess risk.
The difference is the product design and the way each lender approaches the particular transaction.
A bank's standard mortgage process is often well suited to a conventional property purchase. A specialist lender may be better equipped to assess a property investment that depends on a specific works programme, auction timetable and repayment strategy.
8. Are Specialist Lenders More Flexible?
Specialist lenders are often more flexible than mainstream banks when assessing unusual property transactions.
However, flexibility should not be confused with guaranteed approval.
A specialist lender may consider a case outside conventional mortgage criteria, but it will still assess the risks.
Factors may include:
- The property's current value.
- Its condition and proposed works.
- The borrower's experience.
- The available deposit or equity.
- The legal title.
- Planning and regulatory position.
- The proposed exit strategy.
- The loan-to-value ratio.
- The expected repayment timeframe.
Different specialist lenders have different appetites. One may be comfortable with light refurbishment but decline a structural project. Another may support commercial property but not a particular residential security type.
This is where experienced broker-led lender selection can make a difference.
The objective is to identify the lender whose criteria fit the transaction, rather than submitting the same case indiscriminately to multiple providers.
9. Regulation: Are Banks and Specialist Lenders Regulated Differently?
It is important not to assume that a high street bank is regulated while a specialist lender is not.
The regulatory position depends on the type of lending and the circumstances of the transaction, not simply on the lender's business model.
Certain residential mortgage and bridging arrangements fall within the Financial Conduct Authority's regulated mortgage framework. Other business-purpose property finance, including some buy-to-let and bridging arrangements, may be unregulated, subject to the applicable definitions and exemptions.
A specialist lender can offer regulated products, and a bank can offer lending that is not regulated as a residential mortgage.
For borrowers, the important questions include:
- Is the proposed loan regulated or unregulated?
- Is the property being used as the borrower's home?
- What is the purpose of the borrowing?
- What protections and complaint routes apply?
- Is the adviser appropriately authorised for the activity?
The regulatory classification should be confirmed for the actual transaction. It should never be inferred simply from whether the lender is a bank or specialist finance provider.
10. How to Choose the Right Lender for Your Next Property Investment
Before approaching a lender, establish what the transaction actually requires.
A useful starting point is to work through the following questions.
1. Is the property mortgageable today?
If it is habitable, standard and suitable for conventional lending, a bank mortgage may be appropriate.
If it is uninhabitable, requires substantial works or has unusual characteristics, investigate specialist options.
2. How quickly must the transaction complete?
Check the contractual completion date and work backwards.
Do not rely on a lender's general advertised processing time. Ask whether the specific case can realistically complete within the available period.
3. What is the purpose of the borrowing?
Are you buying a rental property, refurbishing an asset, developing a site or acquiring a commercial investment?
Different objectives require different products.
4. What is the exit strategy?
If you are using bridging finance, identify how the loan will be repaid.
Will you refinance, sell or use another repayment source? Has that route been investigated and costed?
5. What is the true cost of the finance?
Compare the total costs over the expected loan term, including interest, fees, valuation, legal costs and potential exit charges.
6. Does the lender understand the asset?
A lender's willingness to finance property of a particular type matters.
Ask whether it has appetite for the specific property condition, title, tenure, location and proposed use.
7. What happens if the project takes longer?
Understand the loan maturity date, extension provisions, additional charges and consequences of delayed repayment.
Do not assume a lender will automatically extend a facility.
11. The Auction360 Approach: Specialist Entry, Term Exit
At Auction360, we view property finance as part of the overall investment structure.
The funding should support the purchase, the project and the intended repayment strategy.
For an auction property requiring refurbishment, this may mean arranging specialist finance for the acquisition and works, then planning a suitable long-term refinance once the property meets the relevant mortgage criteria.
For a straightforward buy-to-let purchase, a conventional mortgage may be more appropriate from the outset.
The objective is not to use specialist finance unnecessarily. It is to use the right finance at the right stage.
Explore the relevant Auction360 services:
For investors purchasing additional residential property, remember to calculate the relevant property transaction tax before bidding. In England and Northern Ireland, higher SDLT rates may apply to additional residential property purchases, including qualifying company purchases. The precise treatment depends on the buyer, property and transaction. Use the GOV.UK SDLT guidance and obtain appropriate tax advice.
Frequently Asked Questions
1. Is a specialist lender more expensive than a high street bank?
Usually, specialist bridging and development finance carry higher headline rates than conventional long-term mortgages. However, they may provide funding for transactions that a mainstream bank cannot support. The right comparison is the total cost of a suitable finance solution, not simply the headline interest rate.
2. Why can't high street banks always fund property auction purchases?
Some can, particularly where the property is mortgageable and the finance is arranged early enough. However, many auction purchases have short completion deadlines, and some properties require refurbishment or have unusual characteristics. These factors can make conventional mortgage processing and underwriting unsuitable.
3. What is the hybrid funding structure?
It is a two-stage approach. A specialist lender provides short-term finance for the acquisition and potentially the refurbishment. Once the property is improved and meets the relevant lending criteria, the investor refinances onto a longer-term mortgage, which may be from a high street bank or another suitable lender.
4. How much does specialist bridging finance cost?
The cost depends on the lender, borrower, property, loan size and term. As an illustration, an £84,000 facility at 0.85% per month for nine months, with interest serviced monthly, produces £6,426 in interest. Arrangement fees, exit fees, legal costs, valuation charges and other costs would be additional.
5. Do specialist lenders fund uninhabitable properties?
Some do. Refurbishment bridging and development finance products may be available for properties that do not meet conventional mortgageability requirements. Acceptance depends on the property, works, valuation, borrower and lender criteria.
6. Which lender is faster?
Specialist lenders can often offer a faster process for suitable cases, particularly where the transaction needs individual underwriting. However, speed is not guaranteed. Legal work, valuation, property complexity and the completeness of the application all affect the timetable.
7. Are specialist lender declines negotiable?
Sometimes. A specialist underwriter may explain which aspects of a case fall outside its appetite and whether a revised structure could be considered. However, not every decline can be overcome. The lender must still be satisfied that the transaction meets its criteria.
8. Are high street banks and specialist lenders regulated differently?
Not simply because of their business models. The regulatory position depends on the type and purpose of the loan, the borrower and the property. Both types of lender can offer products within the regulated mortgage framework, while some business-purpose lending may be unregulated.
9. How do the two models assess the same property differently?
A conventional mortgage lender generally focuses on borrower affordability and whether the property meets its security requirements. A specialist lender may additionally assess the property's current condition, the proposed works, the investment plan and the exit strategy. Both assess risk, but their products and underwriting approaches differ.
10. How should I choose between a high street bank and a specialist lender?
Start with the property and the transaction. If the property is standard, mortgageable and there is sufficient time to complete, compare conventional mortgage options. If it is an auction purchase with a tight deadline, requires significant refurbishment or has complex characteristics, investigate specialist finance. Where appropriate, plan a refinance onto longer-term finance from the beginning.
Conclusion: Choose the Lender That Fits the Investment
The high street bank versus specialist lender debate is often presented as a simple question of cost.
That misses the bigger issue.
A conventional bank mortgage may be cheaper for a standard buy-to-let property, but it cannot necessarily support a purchase that needs to complete quickly or involves unmortgageable security.
A specialist lender may provide the flexibility and speed required to acquire and improve that property, but its higher interest rate makes it less attractive as a permanent funding solution.
For many auction investors, the sensible structure is to use specialist finance for the short, demanding phase and then refinance onto a suitable long-term mortgage once the property is ready.
The important point is to plan both stages before committing to the purchase.
The best lender is not automatically the one with the lowest headline rate. It is the lender whose product, criteria and timetable fit the property investment you are actually trying to complete.
That is how investors avoid paying for the wrong finance, missing auction deadlines and turning an otherwise promising property opportunity into an expensive mistake.
About the Author
Deji Nehan is the author of Auction Demystified: Unlocking Auction Success and has more than 15 years' experience in property auctions and property finance. He is the founder of Auction360, a platform focused on auction finance, bridging finance and practical support for property investors navigating auction transactions.
Learn more about the book: Auction Demystified: Unlocking Auction Success.
Disclaimer
This article is for general educational purposes only and does not constitute financial, legal, tax or investment advice. Finance is subject to lender criteria, valuation, underwriting and contractual terms. Interest rates and fees are indicative and may change. Borrowers should obtain appropriate professional advice before entering into a finance agreement. Your property may be repossessed if you do not keep up repayments on a mortgage or other debt secured against it.