Bridging Loan Interest: Retained, Rolled or Serviced? Which Payment Method Fits Your Deal?
Introduction: Three ways to pay bridging loan interest
When arranging a bridging loan, the interest rate is only part of the financial decision. You also need to understand how the lender expects that interest to be paid.
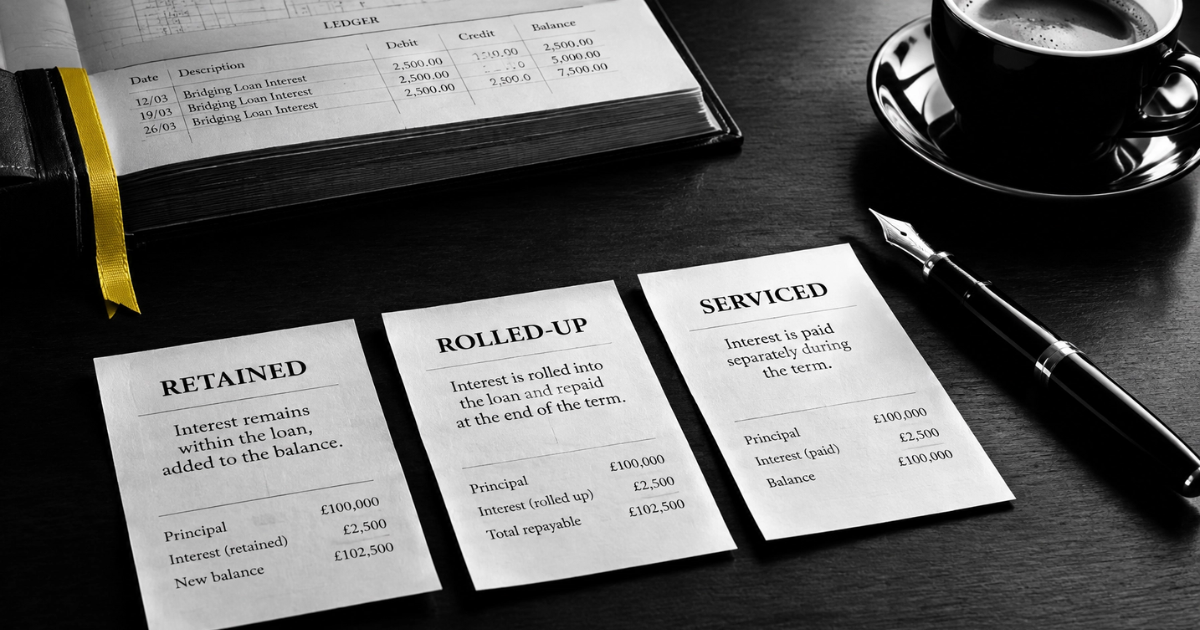
Most bridging facilities use one of three structures:
- Retained interest: the lender calculates interest upfront and deducts it from the loan advance.
- Rolled-up interest: interest is added to the outstanding balance and repaid when the loan is redeemed.
- Serviced interest: you pay the interest monthly from your own funds.
There is also a hybrid option known as part-retained interest, where interest is retained for an initial period and then paid monthly.
These structures can produce very different cashflow requirements, net loan proceeds and redemption balances. The right choice depends on the property, the project, the expected exit and—most importantly—whether you can genuinely afford monthly interest payments.
Consider an auction purchase where your available cash is already committed to the deposit, Stamp Duty Land Tax (SDLT), legal costs and refurbishment. A monthly interest payment could put pressure on the project. On the other hand, if you own a rental portfolio generating reliable income, servicing interest may be more economical than allowing it to accumulate.
This guide compares all three methods using the same £100,000 example, explains how lenders assess them and considers what happens when a project takes longer than expected.
Market position: October 2026. All rates and calculations are illustrative, not lender quotations. Actual terms depend on the lender, facility structure, borrower, property and exit strategy.
“Retained, rolled or serviced is not paperwork. It is the difference between surviving the works and funding them twice.”
— Deji Nehan, Auction Demystified: Unlocking Auction Success
1. Key takeaways: retained, rolled-up and serviced interest
| Interest structure | How it works | Main cashflow implication |
|---|---|---|
| Retained | Interest is deducted from the advance upfront | No monthly interest payment, but you receive less money initially |
| Rolled-up | Interest is added to the loan balance | No monthly payment, but the redemption balance grows |
| Serviced | Interest is paid monthly | You need regular cashflow, but the principal does not increase through unpaid interest |
| Part-retained | Interest is retained for an agreed period and serviced afterwards | Combines an initial payment-free period with later monthly payments |
The important distinctions are:
- Retained interest reduces the net amount released to you at drawdown.
- Rolled-up interest increases the amount you owe over time because interest is charged on an increasing balance.
- Serviced interest requires monthly payments but prevents the interest balance from accumulating.
- The lender's underwriting criteria determine which structures are available. You cannot assume that every lender will offer all three.
- A longer term makes the choice more significant, particularly where interest compounds.
2. Retained interest: deducted from the advance
Retained interest is one of the most familiar structures in auction finance and refurbishment bridging.
The lender calculates the interest for an agreed period at the outset and deducts that amount from the gross facility. You receive the remaining advance, subject to any other deductions, while the agreed principal remains payable when the loan is redeemed.
Worked example: £100,000 retained-interest facility
Assume:
- Gross loan: £100,000
- Monthly interest rate: 0.85%
- Agreed term: 9 months
- Interest treatment: retained
The calculation is:
£100,000 × 0.85% × 9 = £7,650
| Item | Amount |
|---|---|
| Gross facility | £100,000 |
| Retained interest | £7,650 |
| Net advance before other fees | £92,350 |
| Principal payable at redemption | £100,000 |
You receive £92,350 before arrangement fees and other deductions. At redemption, you repay the £100,000 principal, assuming no additional interest, fees or charges have become payable.
The key point is that the retained interest is not added to the £100,000 redemption balance in this example. It has already been deducted from the advance.
Why retained interest is popular with auction buyers
Auction buyers frequently need to preserve cash for several competing commitments:
- The auction deposit and remaining purchase balance.
- SDLT and buyer's premium.
- Solicitor and valuation costs.
- Immediate repairs and refurbishment.
- Contingency funds for unexpected work.
A property undergoing refurbishment may also generate no rental income during the works. Requiring monthly interest payments in those circumstances can create unnecessary pressure.
Retained interest removes that monthly payment obligation for the agreed retained period. It can therefore make cashflow easier to manage while the property is being improved.
The retained-interest detail borrowers must check
Retained interest is not automatically the cheapest or safest option in every situation.
There are two contractual details to establish before accepting the facility:
1. What happens if you repay early?
Check whether the lender refunds unused retained interest if the loan is redeemed before the agreed term. The treatment depends on the facility agreement. Do not assume that early redemption automatically produces a pro-rata refund.
2. What happens if the loan runs beyond the retained period?
If your retained period ends but the loan remains outstanding, further interest may become payable. The lender may collect it at redemption or apply the agreed extension arrangements.
This is why your projected term should include realistic contingency time for refurbishment, valuation, conveyancing and refinance.
An £84,000 auction finance example
Consider a borrower arranging an £84,000 facility at 0.85% per month for nine months.
The retained interest is:
£84,000 × 0.85% × 9 = £6,426
The advance after retained interest is:
£84,000 ? £6,426 = £77,574
That is before any arrangement fee or other deductions.
The borrower still owes the £84,000 principal at redemption, assuming the facility is redeemed within the agreed terms and no additional charges arise.
This distinction matters when preparing an auction bid. A facility advertised as £84,000 does not necessarily mean £84,000 will arrive in your bank account.
The gross facility, net advance and redemption amount must all be included in your funding model before you bid.
3. Rolled-up interest: added to the loan balance
Rolled-up interest works differently.
Instead of paying interest monthly or having the full agreed interest deducted at drawdown, the interest is added to the outstanding balance. You repay the accumulated balance when the property is sold or refinanced.
Where the lender compounds interest monthly, each month's interest is calculated on the growing balance rather than only the original principal.
Worked example: £100,000 rolled-up facility
Assume:
- Gross loan: £100,000
- Monthly interest rate: 0.85%
- Term: 9 months
- Interest treatment: rolled-up and compounded monthly
The balance grows as follows:
| Month | Outstanding balance |
|---|---|
| 0 | £100,000 |
| 3 | £102,577 |
| 6 | £105,189 |
| 9 | £107,838 |
The calculation after nine months is approximately:
£100,000 × (1.0085)? = £107,838
The accumulated interest is therefore approximately £7,838.
The borrower has made no monthly interest payments, but the amount required to redeem the facility has increased.
Why rolled-up interest costs more
The difference comes from compounding.
With simple interest, each month's interest is calculated on the original principal. With monthly compounding, unpaid interest becomes part of the balance on which subsequent interest is calculated.
That means the interest itself starts generating further interest.
At 0.85% per month, the difference may look relatively small over nine months. However, it becomes more significant as the loan amount and term increase.
For this reason, borrowers should not compare bridging offers using the headline monthly rate alone. The method of calculation and the projected redemption balance are equally important.
When rolled-up interest makes sense
Rolled-up interest can be appropriate where:
- The property generates no rental income during the loan.
- The borrower wants to preserve cash for construction or refurbishment.
- The project has a longer works programme.
- There is a clear and credible sale or refinance exit.
- The borrower has sufficient financial capacity to meet the eventual redemption amount.
It may be useful for heavy refurbishment or development projects where cash is needed to complete the works rather than service monthly interest.
However, rolled-up interest should not be treated as free finance. It postpones the payment; it does not remove it.
4. Serviced interest: paid monthly
With serviced interest, the borrower pays the interest each month from their own funds.
The outstanding principal remains unchanged, provided all payments are made and no other charges are added to the facility.
Using the same example:
- Gross loan: £100,000
- Monthly interest rate: 0.85%
- Monthly interest payment: £850
- Term: 9 months
The calculation is:
£100,000 × 0.85% = £850 per month
Over nine months:
£850 × 9 = £7,650
At the end of the term, the borrower still owes the original £100,000 principal, assuming no other additions to the balance.
Why serviced interest can be cheaper
At the same headline rate, simple retained interest and serviced interest produce the same £7,650 interest cost over nine months in this illustration.
Serviced interest avoids the compounding effect of rolled-up interest. Some lenders may also offer a more competitive rate for serviced facilities because the borrower is paying interest regularly rather than allowing it to accumulate.
However, the actual rate difference is lender-specific. It is not guaranteed that a serviced facility will always have a lower headline rate.
The cashflow test
The biggest disadvantage is the monthly commitment.
You need a dependable source of funds to meet the payment throughout the term, including any extension period.
Possible sources include:
| Income source | When it may support serviced interest |
|---|---|
| Existing rental portfolio | Rental income from other properties can cover the monthly commitment |
| Rent from the property being purchased | Relevant where the property is already tenanted and the income is available to the borrower |
| Salary or business income | May support payments, subject to the lender's affordability and underwriting requirements |
| Sale or refinance proceeds | Usually not suitable for monthly servicing because the proceeds arrive at the exit rather than during the term |
A borrower should not choose serviced interest simply because it produces an attractive total-cost comparison.
If the monthly payment puts pressure on household or business finances, the structure may create more risk than it removes.
The question is not just whether you can afford £850 this month. It is whether you can comfortably afford it every month until the facility is redeemed.
5. The same £100,000 loan: side-by-side comparison
The following table compares the three main structures at 0.85% per month.
| Treatment | Interest over 9 months | Interest over 12 months | Monthly cash required | Balance at exit |
|---|---|---|---|---|
| Retained | £7,650 | £10,200 | £0 during retained period | £100,000 |
| Rolled-up | Approx. £7,838 | Approx. £10,667 | £0 | Approx. £107,838 or £110,667 |
| Serviced | £7,650 | £10,200 | £850 | £100,000 |
The retained figures assume simple interest is calculated upfront for the agreed period. The rolled-up figures assume monthly compounding. The serviced figures assume the same 0.85% rate throughout and that payments are made on time. Fees, charges and extension costs are excluded.
What the numbers tell you
Retained interest preserves monthly cashflow but reduces the amount you receive at drawdown. It can suit an auction purchase where the borrower needs to fund the acquisition and works without monthly interest payments.
Rolled-up interest also avoids monthly payments, but the redemption balance increases through compounding. It can suit projects with no income during the term, provided the exit can comfortably support the larger balance.
Serviced interest requires monthly cash but keeps the principal stable. Where the borrower has reliable income and the rate is competitive, it can be the more economical structure.
The difference between rolled-up and serviced interest is approximately £188 over nine months and £467 over twelve months in this example. Those figures are not enormous on a £100,000 facility, but the difference increases as the loan size and term increase.
The right decision should therefore be based on the whole project, not just the apparent interest saving.
6. How lenders decide which interest treatment to offer
Lenders do not necessarily allow borrowers to select any interest structure they prefer. The decision is influenced by the property, the borrower's financial position, the proposed use of funds and the exit strategy.
A simplified guide is:
| Case type | Possible interest treatment | Why |
|---|---|---|
| Purchase-only bridge with reliable income | Serviced | Monthly interest may be supported by existing income |
| Auction purchase requiring refurbishment | Retained | Cash may be needed for the purchase and works |
| Heavy refurbishment or development | Rolled-up or part-retained | The project may not generate income during construction |
| Regulated chain-break borrowing | Retained or serviced | Depends on the borrower's circumstances and lender assessment |
| Commercial or complex property | Case-specific | Structure depends on the asset, cashflow and exit |
The central underwriting question is straightforward:
Can the borrower afford to service the interest monthly without undermining the project?
If the answer is yes, serviced interest may be available. If not, the lender may consider retained or rolled-up interest, subject to the facility's loan-to-value limits, net advance and exit affordability.
A lender will also consider whether the proposed exit is realistic. A refinance that depends on a property reaching a particular valuation after extensive works needs to be supported by credible figures, not optimism.
7. Part-retained interest: the hybrid option
Borrowers sometimes assume that the choice is limited to paying all the interest upfront, rolling it all up or servicing it from the first month.
That is not always the case.
Some lenders may offer a hybrid structure known as part-retained interest.
Under this arrangement, interest is retained for an agreed initial period and then serviced monthly.
Example: six months retained, followed by six months serviced
Imagine a refurbishment project that is expected to become a tenanted rental property after five months.
The lender might structure the facility so that:
- Interest is retained for the first six months.
- The borrower pays interest monthly from month seven.
- The property is expected to generate rental income after refurbishment and letting.
At £100,000 and 0.85% per month, the illustrative interest is:
- First six months: £5,100 retained.
- Next six months: £850 per month.
- Total interest over twelve months: £10,200.
This is broadly equivalent to twelve months of simple interest at the same rate, assuming no additional charges or rate changes.
The advantage is that the borrower does not need to fund monthly interest while the property is undergoing works, but can move to monthly payments once income becomes available.
Not every lender offers this structure, and the terms need to be agreed before completion. Ask your broker whether a part-retained arrangement is possible if your project has a clear transition from refurbishment to rental income.
8. What happens if your bridging loan runs beyond the agreed term?
A bridging loan should be arranged around a realistic exit timetable. However, refurbishment delays, legal complications, valuation issues and slow property sales can all extend a project.
The interest structure affects how that extension changes your financial position.
| Treatment | What happens during an extension? | Main cost consideration |
|---|---|---|
| Retained | Interest may become payable beyond the retained period | Additional interest and any extension charges |
| Rolled-up | Further interest is added to the outstanding balance | Compounding continues to increase the redemption figure |
| Serviced | Monthly payments continue | Interest remains payable, alongside any agreed extension charges |
Retained interest: the retained period matters
If your facility includes nine months of retained interest but takes twelve months to redeem, you need to understand how the lender charges for the additional three months.
The original retained amount may cover only the agreed nine-month period. Further interest could be payable at redemption or under the lender's extension arrangements.
Rolled-up interest: the balance keeps growing
With rolled-up interest, an extension increases the balance on which future interest is calculated.
This can become expensive if the project is already under pressure.
A delayed refinance combined with a growing loan balance may reduce the equity available to the borrower.
Serviced interest: monthly payments continue
Serviced interest is more predictable in the sense that the principal does not grow through unpaid interest, provided payments continue.
However, you must maintain the monthly payments for longer than originally planned. Extension fees and other contractual charges may also apply.
Build contingency into the original term
Do not arrange a bridging loan based solely on the best-case completion date.
Allow time for:
- Refurbishment and contractor delays.
- Building control or certification requirements.
- Tenant finding and letting.
- Valuation and lender underwriting.
- Solicitor enquiries and conveyancing.
- Property marketing and sale completion.
A realistic term with contingency is usually safer than relying on an extension to rescue an optimistic project timetable.
9. How to choose the right interest structure for your deal
The best structure is the one that supports the project's cashflow and leaves a credible route to redemption.
Use these questions when comparing bridging finance offers:
1. Will the property generate income during the loan?
If not, monthly servicing may be difficult unless you have another reliable income source.
2. How much cash do you need at completion?
Retained interest reduces the net advance. Make sure the money released is sufficient to complete the purchase and fund the immediate costs.
3. Can the exit support the redemption balance?
For rolled-up interest, calculate the projected balance at the expected redemption date, including the effect of any extension.
4. How long will the project realistically take?
A short-term purchase bridge and a twelve-month refurbishment project have different cashflow requirements.
5. What happens if you redeem early or late?
Check the lender's treatment of unused retained interest, additional interest, extension fees and early repayment.
6. Are the quoted rates genuinely comparable?
Compare the monthly rate, calculation method, gross facility, net advance, fees and total redemption figure. A lower headline rate does not automatically mean a cheaper facility.
10. How Auction360 approaches bridging loan interest
At Auction360, the interest structure should be considered alongside the purchase price, refurbishment budget and exit strategy—not as a separate administrative decision.
For an auction purchase, the borrower needs to understand how much funding will actually be released, what cash must be contributed and how much will be required to redeem the facility.
Our approach is to consider:
- The gross loan and expected net advance.
- The interest structure and total projected interest.
- Arrangement, valuation, legal and exit fees.
- The amount of cash required for the auction purchase.
- Refurbishment costs and contingency.
- The proposed refinance or resale exit.
- The financial impact of a delayed completion or extended term.
Explore our bridging finance service and auction finance service.
If you are preparing to bid, our pre-auction approval service can help you assess the funding structure before you commit to the purchase.
The objective is not simply to secure a loan. It is to arrange finance that gives the project enough cashflow to reach a successful exit.
Frequently asked questions
What is retained interest on a bridging loan?
Retained interest is calculated upfront for an agreed period and deducted from the gross loan advance. You do not normally make monthly interest payments during that retained period, but you receive less money at drawdown. The principal remains payable at redemption, subject to the facility terms.
What is rolled-up interest on a bridging loan?
Rolled-up interest is added to the outstanding loan balance and repaid when the facility is redeemed. Where the lender compounds interest, each month's interest is calculated on the increasing balance, so the total cost can rise faster than simple interest.
What is serviced interest on a bridging loan?
Serviced interest is paid monthly by the borrower. The principal generally remains unchanged, provided payments are maintained and no other charges are added. It requires reliable monthly cashflow.
Which bridging loan interest method is cheapest?
At the same monthly rate, retained and serviced interest can have the same total interest cost under a simple-interest calculation. Rolled-up interest costs more where it compounds. However, serviced facilities may have different rates, and fees and contractual terms can change the comparison.
Can I choose between retained, rolled-up and serviced interest?
Not always. The lender decides which structures it is willing to offer based on the borrower, property, loan-to-value, project and exit strategy. Your broker can explain the available options and negotiate where appropriate.
What is part-retained interest?
Part-retained interest is a hybrid structure where interest is retained for an initial period and then paid monthly. It can suit a refurbishment project where the property is expected to start generating rental income partway through the loan.
Is retained interest refundable if I repay my bridging loan early?
That depends on the facility agreement. Some lenders may refund unused retained interest on early redemption, while others may apply different contractual terms. Confirm the calculation and refund policy before accepting the offer.
What happens if my bridging loan runs past its agreed term?
The lender may charge additional interest, extension fees or other contractual charges. Retained interest may cover only the original agreed period, rolled-up interest may continue compounding, and serviced payments may need to continue. Contact the lender or broker before the maturity date if you anticipate a delay.
Does rolled-up interest reduce the amount I receive?
Not necessarily at drawdown. Unlike retained interest, rolled-up interest is generally added to the balance over time rather than deducted upfront. However, the net amount you receive can still be reduced by arrangement fees, legal costs and other deductions.
Does the interest structure affect how much I can borrow?
It can. Retained interest reduces the net advance available to complete the transaction, while rolled-up interest increases the eventual redemption balance. Serviced interest requires evidence that monthly payments can be maintained. Each structure can therefore affect the lender's assessment of the overall facility.
Can I use retained interest for an auction purchase?
Yes, retained interest is commonly used in auction finance, particularly where the property needs refurbishment and will not generate rental income immediately. The borrower must still ensure that the net advance and available cash are sufficient to meet the completion deadline and project costs.
How much interest would I pay on a £100,000 bridging loan?
At 0.85% per month, simple interest on £100,000 is £850 per month. That is £7,650 over nine months or £10,200 over twelve months. The final amount depends on the interest structure, lender calculation method, term and any additional charges.
Conclusion: choose the structure that protects the exit
Retained, rolled-up and serviced interest solve different cashflow problems.
Retained interest can preserve cash during an auction purchase or refurbishment. Rolled-up interest can defer payments where the project has no income, but compounding increases the eventual redemption balance. Serviced interest can be economical where the borrower has reliable monthly income and can comfortably maintain payments.
The mistake is to choose a structure simply because it avoids monthly payments or appears cheaper on the headline rate.
Before committing to a bridging facility, compare the net advance, monthly cash requirement, total interest and projected redemption figure. Then test the figures against a realistic exit timetable, including the possibility of delays.
The right bridging loan is not necessarily the one with the lowest monthly rate. It is the one whose funding structure gives the project a realistic chance of reaching its exit without running out of cash.
About the author
Deji Nehan is the author of Auction Demystified: Unlocking Auction Success and has more than 15 years' experience in property auctions and finance. He is the founder of Auction360, a UK auction and bridging finance platform focused on helping property investors understand funding structures, assess auction opportunities and plan their exits.
Discover the book: Auction Demystified: Unlocking Auction Success.
Disclaimer
This article is for general educational purposes and does not constitute financial, legal, tax or investment advice. Bridging finance rates, interest calculations, fees and lender criteria vary. Always review the facility agreement and obtain appropriate professional advice before entering into a secured loan.
Your property may be repossessed if you do not keep up repayments on a mortgage or any other debt secured against it.